Construction Equipment Financing for Contractors
Finance the heavy iron that keeps your job sites moving — excavators, loaders, dozers, backhoes and wheel loaders. New and used equipment, dealer or private party.
If you run a construction company, your equipment is how you make money. Every excavator, loader, dozer, or dump truck on your jobs either builds equity for your business or sits on a rental invoice that you pay every month and never get back. MarCom Capital helps contractors finance the construction equipment they use every day, new or used, from a dealer, an auction, or a private seller, so the machine becomes an asset on your books instead of a recurring expense.
This guide explains how construction equipment financing works, what lenders look for, what affects your rate, and how to get approved without draining the cash you need for payroll, materials, and fuel.
What Is Construction Equipment Financing?
Construction equipment financing is a loan or lease used to buy machinery for a construction business. The equipment you buy secures the financing, which is why it is often easier to qualify for than an unsecured business loan. You make a fixed monthly payment over a set term, usually two to seven years, and at the end of the term you own the machine outright. On a $1 buyout lease, you own it for a dollar at the end.
Because the machine is the collateral, lenders pay close attention to what you are buying: its age, hours, condition, and resale value. Yellow iron like excavators, wheel loaders, and skid steers holds its value well, which makes it some of the most financeable equipment in any industry.
Construction Equipment We Finance
We finance the machines contractors actually run on job sites:
- Excavators: mini, compact, mid-size, and full-size crawlers, plus buckets, thumbs, and breakers
- Skid steers and compact track loaders, with attachments
- Dump trucks: single axle, tandem, tri-axle, and super dumps
- Wheel loaders and backhoe loaders
- Rollers, compactors, and asphalt pavers
- Concrete pumps, mixer trucks, and finishing equipment
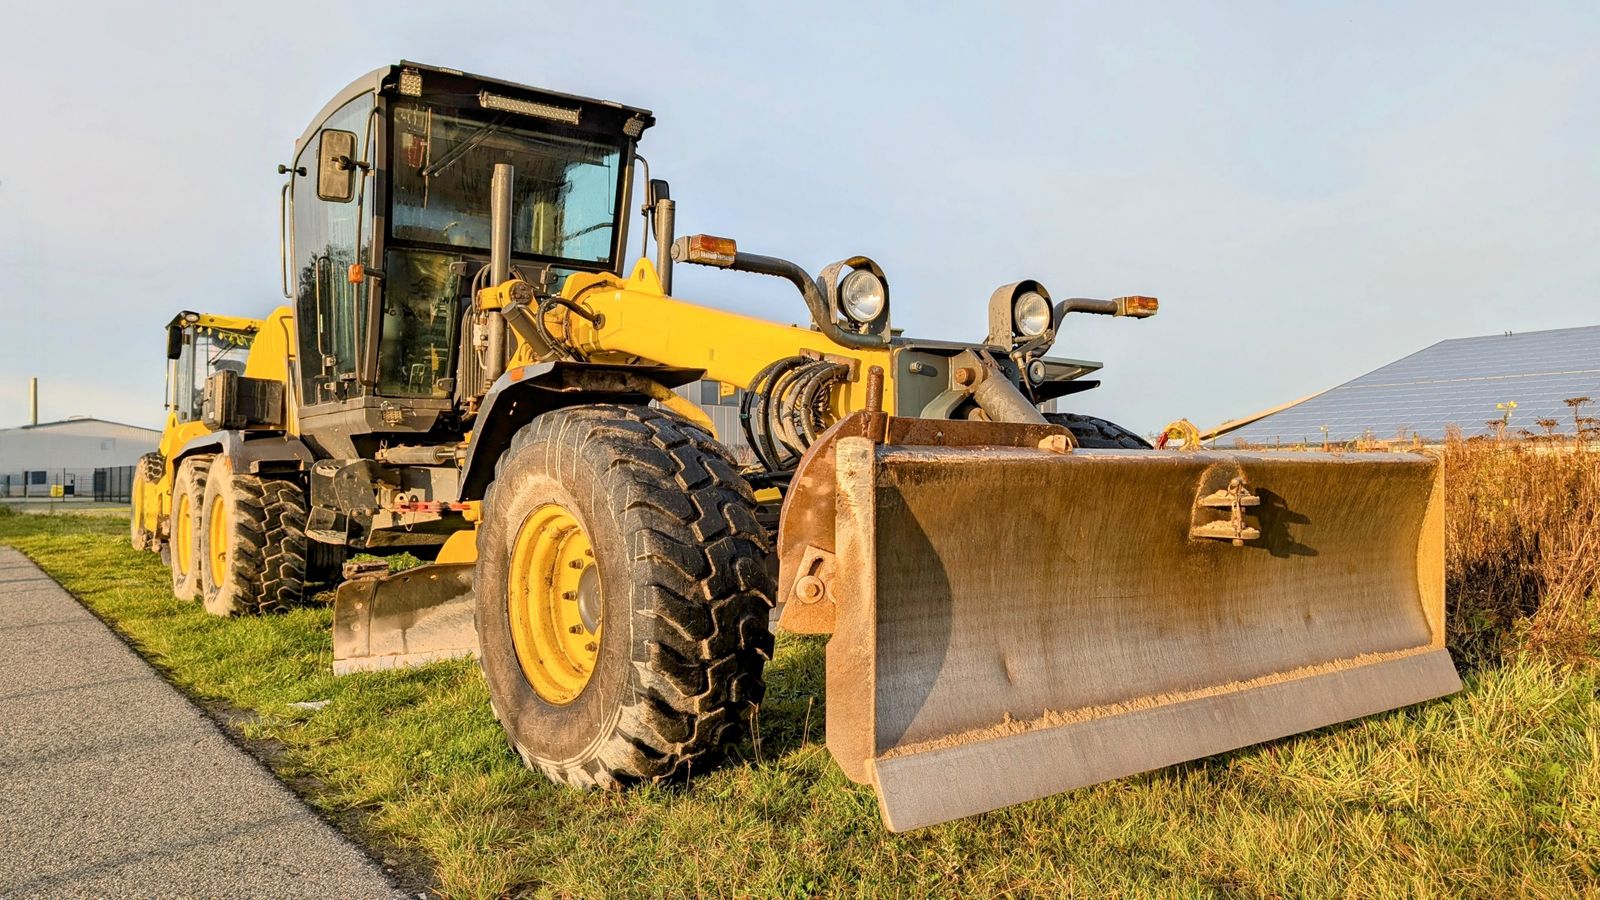
- Dozers, motor graders, trenchers, telehandlers, and equipment trailers
Most contractors we work with finance between $50,000 and $200,000 per deal. Larger fleet purchases, up to $5 million for qualified businesses, are also available.
Who Construction Equipment Financing Is For
Our programs are built for owner-operators and growing construction companies, including:
- Excavation and site work contractors
- Grading and demolition contractors
- Paving and asphalt contractors
- Concrete and foundation contractors
- Landscaping and hardscape contractors
- Utility and underground contractors
- General contractors who self-perform site work
Financing usually makes the most sense in one of two situations. First, you are renting the same type of machine most months of the year. Second, you are turning down work, or bidding smaller jobs than you could handle, because you don't have the equipment.
Finance vs. Rent: The Math Every Contractor Should Run
Renting has its place. According to EquipmentWatch's 2025 State of the Construction Equipment Economy report, 72% of contractors rented equipment in the past 12 months, often for short-term needs or specialty jobs. For a machine you need for two weeks, renting is the right call.
But when a machine is on your jobs most months, rental payments add up fast and leave you with nothing when the job is done. Here is a simple test: add up the last 12 months of rental invoices for one type of machine, then compare that to 12 months of payments on a financed machine. If the numbers are close, financing usually wins, because at the end you own an asset you can keep working, borrow against, or sell.
Ownership also means availability. During peak season, rental yards run short on the exact machines contractors need. When you own the equipment, it is ready when the job is.
How Construction Equipment Financing Works
- 01
Step 1: Apply Online in About 5 Minutes
Our secure application asks for basic business information, owner information, and details on the equipment you want. If you already have a quote or a listing, have it ready.
- 02
Step 2: We Review Your File and Match You With the Right Lender
We work with a network of equipment lenders, including banks and specialty finance companies. We review your file and match it to the lenders most likely to approve the machine and the terms you need, so you are not applying to lender after lender on your own.
- 03
Step 3: Get Your Answer and Get Your Equipment
Once you are approved and sign, the lender pays the seller directly. You pick up the machine and put it to work.
What You Need to Qualify
Every lender is different, but most construction equipment financing decisions come down to a few factors:
- Personal credit score: our programs are built for contractors with 650 or higher.
- Time in business: established businesses get the strongest terms. If your company is newer, ask us about your options.
- Revenue and cash flow: lenders want to see that the monthly payment fits comfortably within your business's income.
- Equipment details: year, make, model, hours, price, and seller information.
- Bank statements: recent business bank statements are often requested for larger amounts.
For a full breakdown, read our guide to heavy equipment financing requirements.
What Affects Your Rate and Terms
Two contractors buying the same excavator can receive very different offers. The biggest factors are your credit profile, time in business, the age and hours of the equipment, your down payment, the term length, and the total amount financed. That is why we don't quote a rate until we have seen your file. Once we do, we will show you real options instead of a teaser number.
New vs. Used Construction Equipment
Used equipment is one of the smartest ways to stretch your budget. Used machines typically cost 30% to 50% less than new, and good yellow iron can run for many years with proper maintenance. Lenders finance used equipment every day, from dealer lots, auctions, and private sellers. For private-party deals, the lender may require an inspection and a lien search before paying the seller. Learn more in our used equipment financing guide.
Tax Benefits: Section 179
Financed equipment can qualify for the Section 179 deduction, just like a cash purchase. For 2026, the Section 179 deduction limit is $2,560,000, and equipment must be purchased and placed in service by December 31, 2026, to count for this tax year. Both new and used equipment can qualify. Talk to your tax professional about your situation, and read our Section 179 guide.
Why Contractors Work With MarCom Capital
- We focus on construction equipment, so we understand the machines and how contractors use them.
- One application gets your file in front of the right lenders.
- We finance new and used equipment from dealers, auctions, and private sellers.
- We are veteran owned and operated.
- We give you a straight answer about where you stand.
Construction Equipment Financing FAQ
Ready to Own Your Next Machine?
Stop paying rent on equipment you could own. Apply in about five minutes, and we will tell you honestly where you stand.
Ready to Finance Your Construction?
See what you qualify for — no obligation.